
Is Lumentum’s AI Boom Already Priced In? What Wall Street’s Earnings Caution Means for LITE Stock

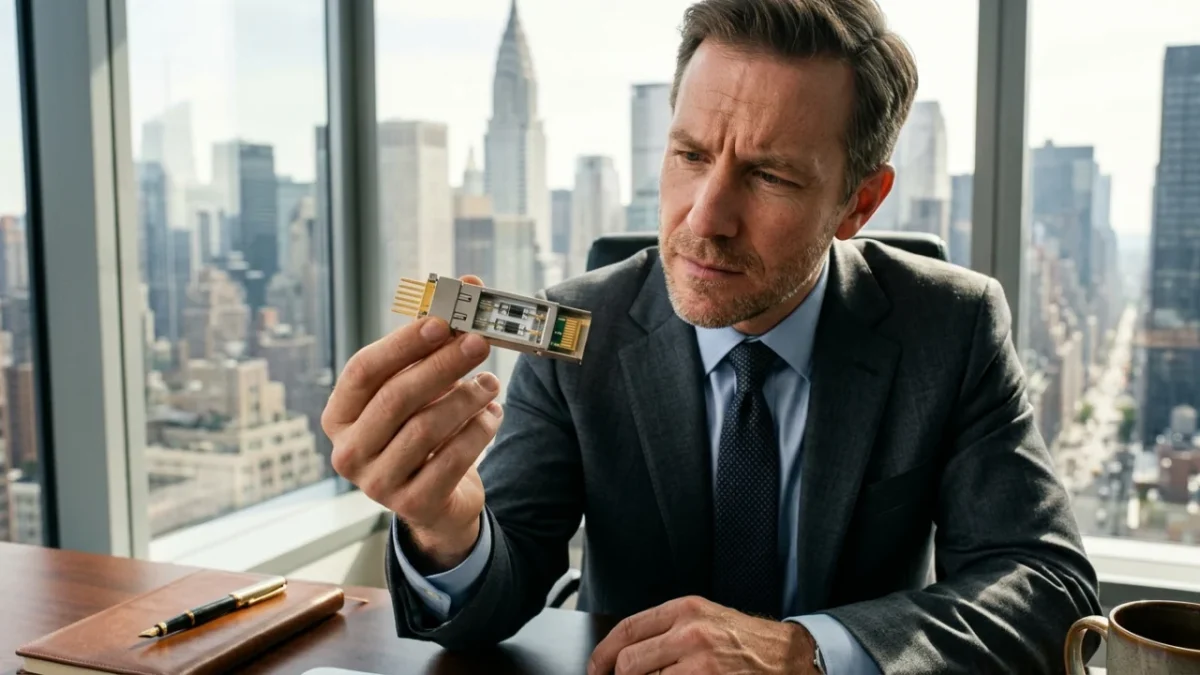
Optical networking pioneer Lumentum Holdings faces a high-stakes earnings checkpoint as market analysts signal that the company’s lucrative artificial intelligence boom may already be fully baked into the valuation. For traders tracking Lumentum LITE stock, the central question is no longer whether optical hardware is critical to hyperscale computing, but whether current multiples leave any room for upside surprises.
When expectations outpace fundamentals, even stellar operational numbers can trigger sharp pullbacks. That delicate balance between explosive AI demand and valuation discipline now defines trading sentiment across Wall Street tech desks.
Understanding where the real risk lies requires stripping away the headlines and examining how high-speed data transmission economics actually translate into corporate cash flow.
The AI Optical Infrastructure Trade: Why Expectations Are Stretched
Lumentum designs and manufactures the specialized laser components and optical transceivers required to connect massive clusters of graphic processing units across enterprise data centers. As AI clusters expand, legacy copper connections hit physical limits in bandwidth and energy consumption.
This dynamic created massive tailwinds for optical hardware specialists. Yet high demand does not guarantee perpetual stock momentum.
When market consensus already anticipates flawless execution and aggressive forward guidance, meeting expectations is rarely enough to drive share prices higher.
Investors frequently confuse long-term secular adoption with immediate equity returns. When a stock rallies heavily leading into an earnings report, even a minor guidance revision or a temporary dip in gross margins can spark sudden volatility.
Myth vs. Reality: Untangling the Optical Tech Narrative
A widespread assumption among retail traders is that every hardware supplier linked to generative AI data centers will see uninterrupted multiple expansion. Historical semiconductor and optical cycles tell a very different story.
- The Myth: Surging demand for cloud transceivers shields optical equipment manufacturers from cyclical downturns in other revenue streams.
- The Reality: Lumentum remains exposed to broader telecommunications spending cycles, where enterprise networking and traditional carrier capex can remain sluggish even as cloud hyperscalers accelerate spending.
Optical component manufacturing is capital-intensive and historically cyclical. A surge in cloud transceiver orders must be weighed against customer concentration risks, where a handful of mega-cap tech buyers wield massive pricing leverage.
Core Tensions Shaping LITE Valuation
To navigate the current risk-reward profile, institutional desks look closely at the trade-offs between growth catalysts and structural headwinds.
| Factor | Market Impact |
|---|---|
| Hyperscale Cloud Demand | Strong order visibility for high-speed laser diodes and coherent optical solutions. |
| Valuation Compression Risk | Elevated price-to-earnings multiples make guidance misses significantly more punishing. |
| Telecom Carrier Spending | Slow recovery in traditional network upgrades tempers total top-line acceleration. |
| Component Competition | Pricing pressure from competing transceiver makers can squeeze gross operating margins. |
Key Metrics Investors Must Track in SEC Filings
Evaluating Lumentum LITE stock during earnings season involves looking beyond the headline revenue and earnings-per-share figures. Sophisticated market participants focus on three specific underlying indicators:
- Gross Margin Trajectory: Tracking whether high-mix transceiver sales offset fixed manufacturing overhead and legacy product line friction.
- Customer Concentration Data: Verifying whether hyperscale revenue is broadening across multiple cloud platforms or relying disproportionately on one anchor client.
- Forward Operating Guidance: Determining whether management commentary supports continued acceleration or points to a mid-cycle digestion period among data center operators.
These underlying levers determine whether a company retains its premium growth multiple or reverts toward standard hardware manufacturing benchmarks.
📱 Trading around high-expectation tech earnings requires strict risk management and a clear focus on forward guidance rather than backward-looking beats.
✨ As the broader optical sector adjusts to shifting capital expenditures from major cloud providers, patience often separates tactical traders from long-term winners.
💬 How are you positioning around hardware and optical suppliers as earnings approach? Drop your thoughts in the comments below and share your strategy with fellow investors.
👇 Join the discussion and let us know where you see optical networking heading over the next market cycle.
 1
 2
 3
 4
