Social Security’s 3.6% COLA Brings a $75 Monthly Raise for Millions of Retirees—but an Accelerated 2032 Trust Fund Depletion Threatens Steep Payout Cuts
Social Security checks are officially receiving a 3.6% cost-of-living adjustment (COLA), boosting the average monthly payout for retired workers by approximately $75. Over 71 million Americans rely on these annual adjustments to keep pace with relentless price increases across basic goods and services.
For disabled workers and survivor beneficiaries, monthly checks will climb by an estimated $59. While that extra cash provides immediate relief, the larger payout masks an escalating financial crisis that could trigger a 22% benefit cut in roughly six years.
Why Is the New Social Security COLA So High?
The latest adjustment marks the fifth-largest Social Security COLA in 35 years. Since 1993, only four annual increases have topped this rate, led by the historic 8.7% bump delivered in 2023.
The push behind this surge stems directly from policy-driven inflation. Recent economic pressures have driven up the consumer price index data evaluated by the U.S. Bureau of Labor Statistics each September, locking in an unusually elevated bump.
The Key Drivers Lifting Inflation Rates
Two distinct policy developments accelerated the prevailing inflation metrics that determine benefit adjustments:
- Import Tariffs and Duties: Broad trade penalties—including temporary duties and actions enacted under Section 301 of the Trade Act of 1974—have raised costs on imported raw materials like steel, pushing domestic manufacturers to pass those price increases to consumers.
- Global Energy Disruptions: Extended conflict-related closures along the Strait of Hormuz created the largest energy supply shock in modern times, sending pump prices for gas and diesel soaring across the country.
A visibly worried couple is reviewing their bills and finances while seated at a table in their home.
The Hidden Cost of Larger Benefit Checks
Bigger checks provide vital support at the grocery store, but they accelerate a math problem inside Washington’s ledgers. The program’s financial footing depends entirely on balancing revenue against outgoing claims.
The Social Security Board of Trustees Report now projects an unfunded long-term obligation reaching a staggering $29.3 trillion over the next 75 years.
The primary concern centers on the Old-Age and Survivors Insurance (OASI) trust fund, which disburses monthly checks to retirees and their survivors. Rising payouts drain reserve balances far faster than government forecasters initially modeled.
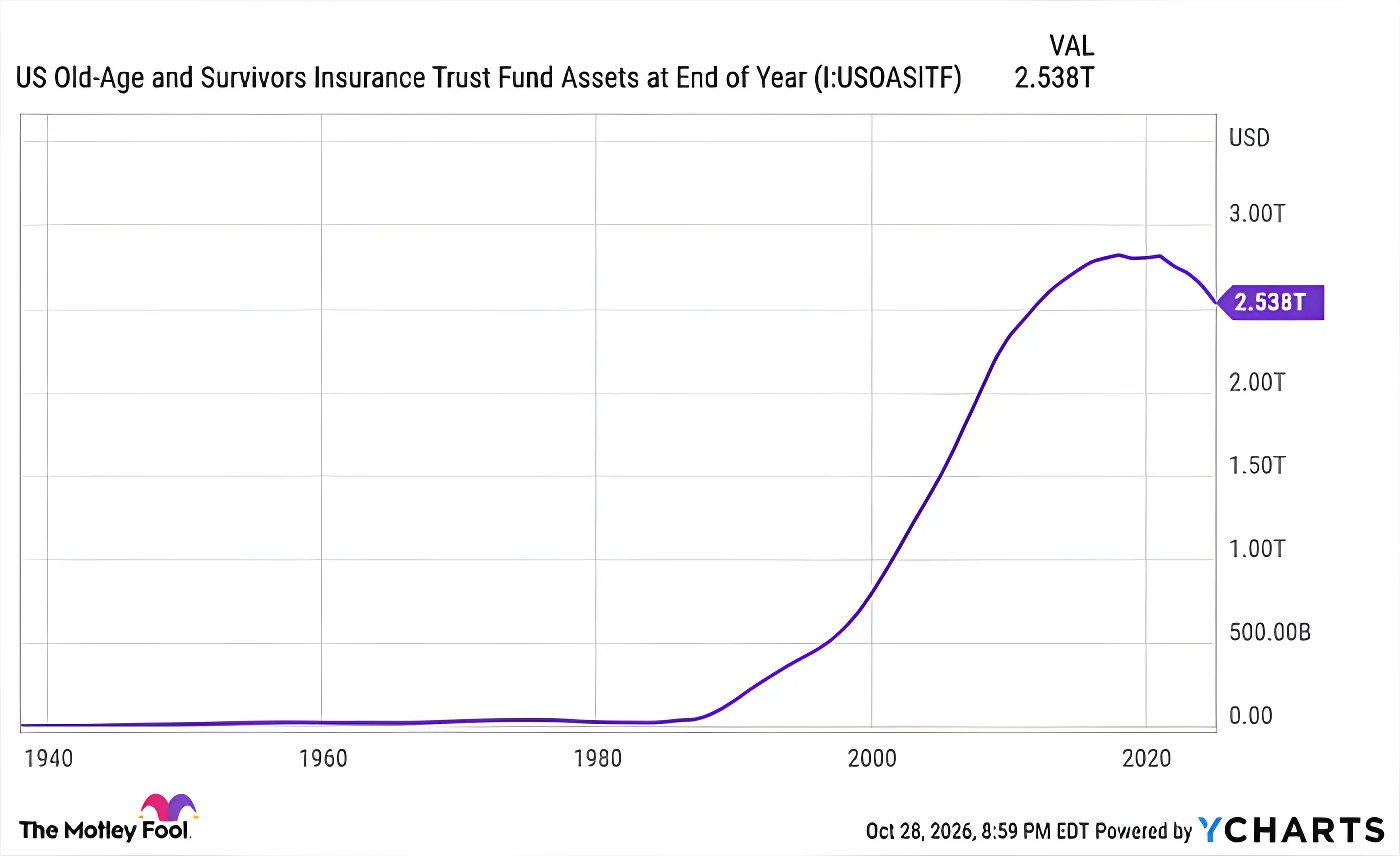
US Old-Age and Survivors Insurance Trust Fund Assets at End of Year Chart
Fact Check: Is Social Security Truly Going Bankrupt?
A widespread public myth claims that when reserve funds hit zero, Social Security will vanish entirely. That misconception is false.
Social Security cannot go bankrupt because over 91% of its funding flows continuously from the 12.4% payroll tax assessed on earned income. As long as Americans work and pay taxes, money continues to flow into the system every single week.
The actual crisis involves payout volume. If the OASI’s asset reserves run dry, incoming tax receipts alone will only cover an estimated 78% of scheduled benefits, forcing an across-the-board 22% reduction.
| Metric | Current Projection |
|---|---|
| Announced COLA Increase | 3.6% |
| Average Retired Worker Raise | $75 per month |
| Average Survivor & Disability Raise | $59 per month |
| 75-Year Unfunded Obligation | $29.3 trillion |
| Projected OASI Reserve Depletion | Fourth Quarter 2032 |
| Estimated Automatic Benefit Cut | 22% |
Why the Depletion Timeline Is Moving Faster
The Trustees previously projected reserve exhaustion in early 2033. Following the passage of major tax and spending legislation alongside compounding, above-average benefit hikes, the timeline shifted forward to the fourth quarter of 2032.
Trustee models assume modest, low-inflation benefit increases over time. Back-to-back outsize adjustments pull billions out of the trust fund years ahead of schedule.
Unless lawmakers enact structural reforms to stabilize asset reserves, that looming six-year cushion could contract even further.
💬 Bigger checks help right now, but the clock on program solvency is ticking faster than expected.
📱 Keeping a close eye on retirement budgets and benefit shifts has never been more critical for American households.
👇 Will a 3.6% raise keep up with your household expenses this year? Share your perspective in the comments below.
 1
 2
 3
 4
