
South Korea’s Tech Whiplash: Why AI Chip Jitters Are Rattling Markets Despite a 1.0% GDP Surge

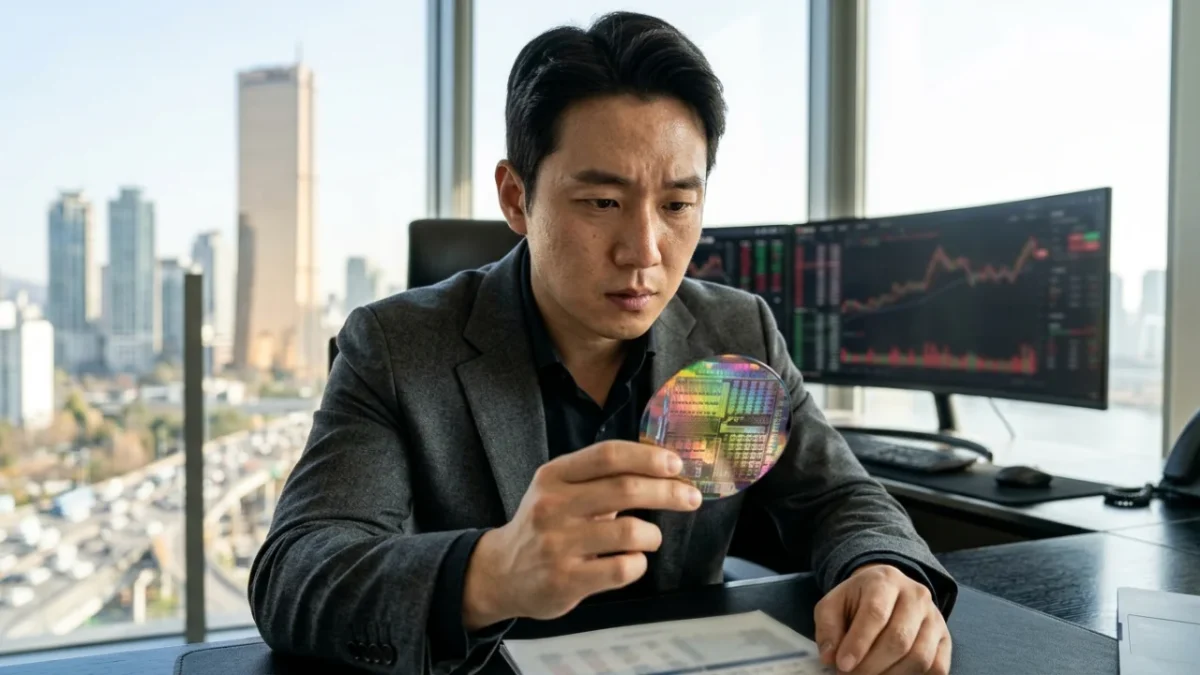
South Korea just beat economic expectations with a 1.0% GDP expansion, yet its benchmark KOSPI index remains stuck in reverse as an aggressive AI market selloff rattles semiconductor equities worldwide. Wall Street and Asian trading floors are wrestling with massive capital expenditures in artificial intelligence that have yet to show matching returns, leaving chip suppliers vulnerable to rapid sell-offs.
The sudden divergence between strong headline economic numbers and sagging equity benchmarks has caught global investors off guard. While domestic manufacturing and exports appear stable on paper, the sheer weight of memory chipmakers on Seoul’s exchange leaves the broader market exposed to every tremor hitting high-tech valuations.
That pressure widened significantly after steep losses swept through global semiconductor powerhouses. With Intel sinking nearly 29% following weak forecasts and Japanese memory firm Kioxia plunging 17%, investors are asking whether the AI infrastructure trade has sprinted far ahead of commercial reality.
Why Strong Economic Growth Failed to Protect the KOSPI
On paper, South Korea’s latest economic report delivered everything equity bulls wanted to see. Gross domestic product expanded by 1.0%, topping analyst projections and confirming resilience across industrial supply chains.
Under the surface, the trading floor tells an entirely different story. The South Korean exchange is heavily weighted toward semiconductor giants like Samsung Electronics and SK Hynix, meaning global sentiment around server hardware and memory chips dictates the direction of the entire market.
When high-profile earnings from mega-cap tech players like Alphabet and Amazon revealed staggering infrastructure bills, market participants began reassessing future margins. Heavy spending on data centers is active, but immediate monetization remains narrow, triggering selective pullbacks across Asian component providers.
Demand for defensive downside protection surged in tandem. The VIX volatility index hit its highest intraday level since April, accompanied by an aggressive spike in put option purchases as institutional desks moved to hedge against deeper declines.
«Questa situazione sembra assomigliare più a una rotazione degli investimenti, accompagnata da una riduzione delle valutazioni, che all’inizio di un deterioramento generalizzato dei mercati», ha evidenziato Florian Ielpo, responsabile della ricerca macroeconomica presso Lombard Odier Investment Management.
The Semiconductor Valuation Reality Check
The turbulence hitting Asian markets stems directly from corporate earnings revisions rather than broader macroeconomic failure. When hardware providers fail to clear sky-high growth benchmarks, trading desks pull liquidity fast.
The contrast across individual suppliers highlights how fractured the landscape has become:
- Intel collapsed by nearly 29% after posting disappointing profit expectations, sending shockwaves through equipment and component partners.
- Kioxia plunged 17% in Tokyo trading, ramping up fears over near-term flash memory margins.
- Tokyo Electron defied the downturn, surging 5.8% after projecting a 50% jump in full-year consolidated net profit.
- Samsung Electronics and SK Hynix staged sharp intra-session swings as traders positioned around customer hardware cycles.
The AI Myth vs. The Market Reality
A prevalent misconception across retail trading communities is that massive spending on artificial intelligence automatically ensures uninterrupted gains for hardware suppliers. The current sell-off proves that aggressive capital expenditure can actually weigh heavily on parent balance sheets before revenue arrives.
Instead of endless margin expansion, hyperscalers face soaring operational overhead. When computing infrastructure costs climb faster than cloud software sales, valuations inevitably contract to match actual cash generation.
| Market Driver | Observed Impact |
|---|---|
| South Korea Headline GDP | Grew 1.0%, outperforming general consensus forecasts |
| KOSPI Benchmark Reaction | Under persistent pressure from semiconductor valuation drag |
| Global Volatility (VIX) | Surged to its highest intraday levels recorded since April |
| Tech Megacap Capex | Heavy spending raised concerns over underlying profit margins |
| Memory Supplier Earnings | Divergent returns driven by uneven enterprise hardware orders |
Navigating the Hardware Sector Rebalancing
Surviving deep sector swings requires focusing on corporate fundamentals rather than market hype. Institutional desks are already filtering component makers through disciplined operational criteria.
- Track customer concentration: Hardware producers relying on a handful of cloud clients carry elevated downside risk when customer capex budgets face scrutiny.
- Monitor cash-flow reinvestment rates: Companies funding aggressive server upgrades out of operating profits hold up better than those stretching balance sheets.
- Watch raw input pressures: Shifting energy and crude costs continue to influence manufacturing margins, with Brent crude moving to $109.91 per barrel and WTI hovering near $100.57.
As the initial wave of indiscriminate AI buying cools, price action across Seoul and Tokyo signals a mature, highly selective market environment. Investors are no longer rewarding tech hardware purely on promise—execution and immediate returns are now non-negotiable.
💬 The disconnect between South Korea’s GDP growth and its stock benchmark reveals just how sensitive global markets have become to hardware spending. Have you experienced this firsthand? Let us know how you are positioning your tech holdings.
📱 Institutional traders are clearly rotating capital away from pure momentum plays toward proven balance sheets. Drop your thoughts in the comments below on where you see chip valuations heading next.
✨ Stay alert to earnings surprises and inventory shifts as hardware cycles continue to reshape tech portfolios worldwide. 👇
 1
 2
 3
 4
