
TSM Stock Price Dips Nearly 6% Even as High-Performance AI Demand Rocketed Quarterly Revenue to $46.7 Billion: What Investors Need to Know

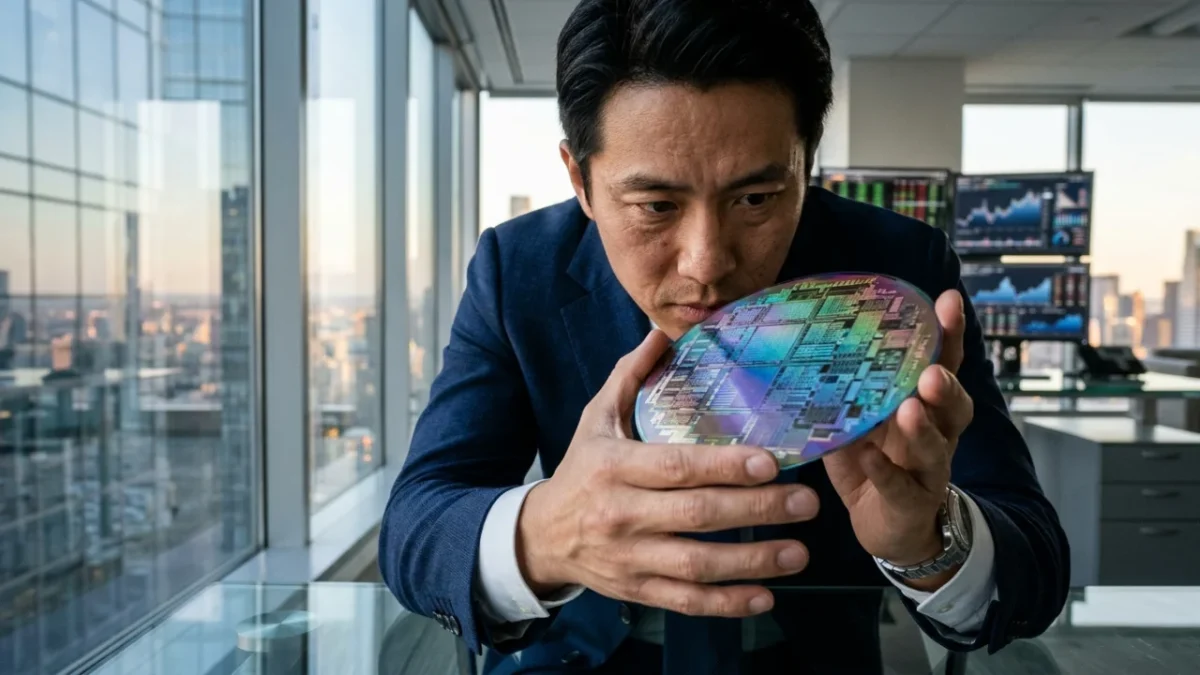
The TSM stock price stumbled with a 5.95% pullback, leaving market watchers stunned after the foundry giant delivered a record-breaking $46.7 billion in quarterly revenue—marking an eye-popping 41.2% year-over-year surge. Despite the single-day selloff, the fundamental powerhouse behind the global artificial intelligence boom is operating at full throttle, creating a sharp contrast between volatile equity trading and underlying foundry demand.
Investors tracking the company are trying to balance phenomenal top-line expansion against broader technology sector turbulence. The core question on Wall Street is simple: does this price correction reflect real structural risks, or is it merely short-term turbulence against an otherwise historic hardware expansion?
The $46.7 Billion Reality Check Behind the Pullback
A widespread misconception on Wall Street suggests that when semiconductor equities fall, end-market chip demand must be evaporating across the board. In reality, the numbers tell an entirely opposite story for leading-edge fabricators.
High-performance computing, which includes specialized AI accelerators and server architecture, surged to represent 68% of total revenue, up dramatically from 57% during the same quarter last year. Rather than slowing down, enterprise investment in AI infrastructure is accelerating at an unprecedented pace.
Furthermore, leading-edge silicon accounts for the lion’s share of production value. Sophisticated, advanced manufacturing technologies made up 79% of wafer revenue, giving the company exceptional pricing power that few competitors can match.
Rising demand for advanced processors supports solid pricing power and long-term expansion, even amid short-term equity volatility.
While contract manufacturing is flourishing, the broader market environment is anything but uniform. Legacy consumer hardware continues to paint an uneven picture across global computing supply chains.
A Tale of Two Chip Giants: Divergent Fortunes
The latest market movements become much clearer when placed beside traditional chip designers like Intel. While Taiwan Semiconductor dipped roughly 6%, Intel shares suffered a staggering 28.58% drop as its consumer-dependent segments lagged behind.
Intel posted $16.5 billion in quarterly revenue, up 21% year over year, with its Data Center and AI unit growing 78% to reach $7.3 billion. Yet its personal computer division contracted by 5%, underscoring how legacy consumer computing continues to drag on diversified chipmakers.
By operating as a pure-play foundry rather than designing its own branded consumer processors, Taiwan Semiconductor avoids direct exposure to soft retail PC demand. Its clients absorb those consumer-facing risks, allowing the foundry to focus capital on the most lucrative, cutting-edge wafer technologies.
| Calendar Period | TSM Quarterly Revenue |
|---|---|
| Late 2024 | $26.8 Billion |
| Early 2025 | $25.5 Billion |
| Mid 2025 | $30.3 Billion |
| Late Summer 2025 | $33.0 Billion |
| Late 2025 | $33.7 Billion |
| Early 2026 | $35.8 Billion |
| Mid 2026 | $40.2 Billion |
| Recent Quarter | $46.7 Billion |
Why Wall Street Hesitated: Unpacking the Volatility
Geopolitics and Capital Allocation Friction
If financial performance remains stellar, why did institutional sentiment waver? Disclosures show shifts among institutional accounts, including firms like Greenleaf Trust trimming 1,518 shares, signaling portfolio adjustments rather than a loss of faith in technology fundamentals.
First, geographic concentration remains an undeniable factor. Having the overwhelming majority of the planet’s advanced chip manufacturing concentrated in a single geographic zone leaves institutional capital permanently sensitive to regional geopolitical developments.
Second, equity analysts are hyper-vigilant regarding enterprise budgets. Any speculative hint that cloud providers or enterprise computing firms might moderate their capital expenditures sends instant shockwaves through semiconductor valuation multiples.
Yet for long-term allocators, the manufacturing moats surrounding sub-nanometer fabrication appear wider than ever. Competitors face enormous capital hurdles and technical bottlenecks trying to replicate high-yield advanced nodes.
📱 Watching your tech holdings navigate market fluctuations requires separating day-to-day valuation noise from fundamental operational dominance.
✨ When looking at the rapid escalation from $26.8 billion to $46.7 billion in quarterly revenue, leading-edge silicon remains the cornerstone of modern compute infrastructure.
💬 Drop your thoughts in the comments below: Is this price pullback a prime buying opportunity, or are geopolitical risks keeping you on the sidelines?
👇 Share this analysis with colleagues and fellow tech investors tracking semiconductor movements.
 1
 2
 3
 4
