The Sandwich Generation Squeeze: Why Generation X Faces an Unprecedented Financial and Caregiving Reckoning Ahead of Retirement
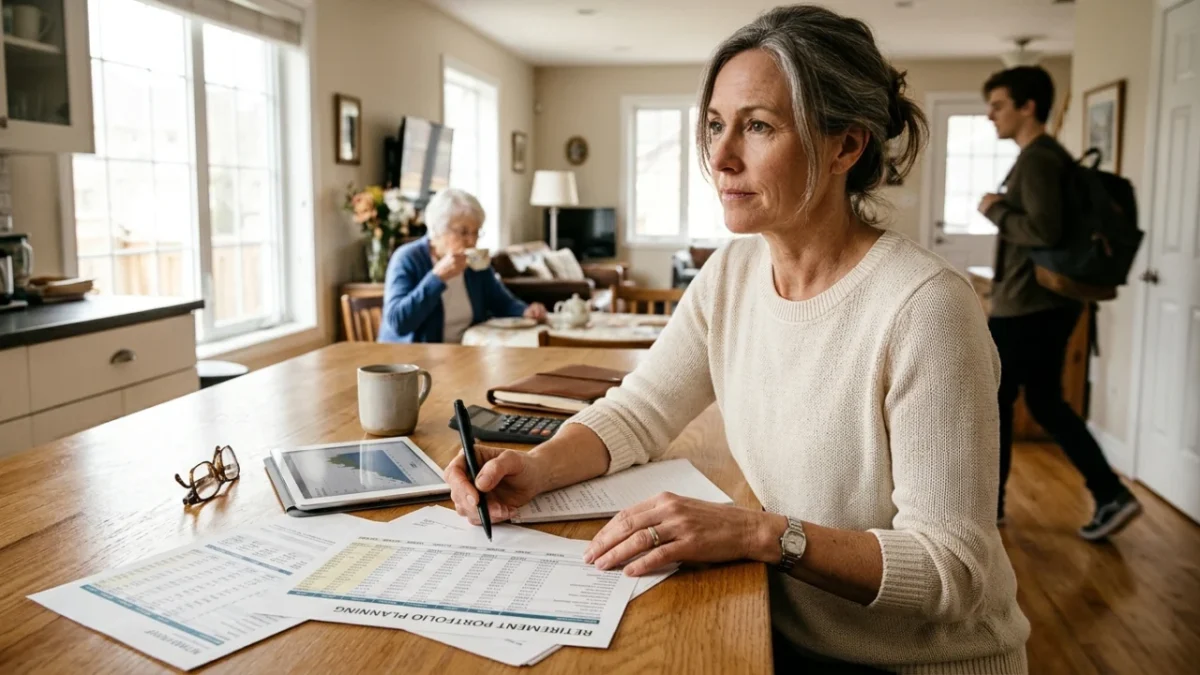
Generation X trends reveal that adults born between 1965 and 1980 now bear the heaviest dual burden of any modern demographic: funding their own fast-approaching retirements while simultaneously financing elderly parents and adult children. This structural squeeze places immense pressure on household balance sheets, fundamentally altering career paths, housing decisions, and long-term financial security.
Often overlooked between larger demographic cohorts, this generation occupies a pivotal role in the economy. They lead major corporations, manage critical public services, and anchor multi-generational households through volatile economic shifts.
Yet the margin for error has narrowed dramatically.
The Double-Sided Pressure of the Sandwich Generation
The defining reality for middle-aged households centers on extended caregiving obligations that run in opposite directions. Aging parents require substantial assistance navigating health care systems, specialized housing, and daily living needs.
At the very same time, prolonged transitions into financial independence have kept young adults reliant on the family home for longer periods. Elevated rental markets, student debt burdens, and competitive entry-level job markets mean adult children frequently lean on parental safety nets well into their twenties.
This dynamic leaves middle-aged wage earners supporting two dependent age groups from a single household budget.
Financial planners consistently observe that caregiving expenses frequently arrive without warning. A sudden health crisis for an elderly relative can instantly redirect capital away from long-term wealth building, forcing families to make painful compromises between immediate care and future solvency.
Retirement Timelines Under Active Negotiation
Unlike earlier generations that relied primarily on defined-benefit pensions, the bulk of this demographic serves as the trial run for defined-contribution retirement accounts, particularly 401(k) plans and individual retirement arrangements.
This structural change shifted the entire burden of market volatility, longevity planning, and investment management onto the individual worker.
The Triple Threat Confronting Wealth Accumulation
When financial analysts examine wealth preservation across middle adulthood, several structural friction points consistently surface:
- The Peak Earning Disconnect: While individuals in their late forties and fifties generally reach their highest annual earnings, non-discretionary family expenditures absorb a disproportionate share of that income.
- Premature Career Departures: A substantial number of mid-career professionals reduce working hours or step away from employment entirely to coordinate care for an incapacitated family member.
- Underfunded Longevity Reserves: Because life expectancies continue to place extended demands on capital, dipping into compound growth accounts creates compounding deficits that cannot easily be recovered later.
These compound realities mean the traditional benchmark of a clean, uninterrupted career exit at age sixty-five is giving way to phased retirement, advisory work, or delayed departures from the workforce.
Workplace Dynamics and the Leadership Handover
Within major corporate and civic institutions, mid-career professionals currently hold the primary operational helm. They hold senior executive ranks, manage complex supply chains, and steer technological integration across legacy infrastructure.
However, workplace priorities among this cohort have evolved sharply. Flexibility, remote autonomy, and health insurance depth now consistently rank above ceremonial titles or speculative stock incentives.
Having navigated multiple macroeconomic disruptions over three decades, experienced professionals prioritize operational resilience. They emphasize durable emergency funds, manageable personal debt ratios, and transparent workplace policies that accommodate family responsibilities.
Proactive Strategies for Protecting Long-Term Security
Mitigating these financial cross-currents requires disciplined structural intervention rather than passive hope. Experts recommend that individuals review estate plans, healthcare power of attorney documents, and parental living wills long before an acute medical episode forces emergency choices.
Establishing explicit financial boundaries with young adult family members also protects the core retirement foundation. Setting defined timelines for financial independence preserves the compound interest required to sustain decades of non-working life.
Because tax frameworks and contribution limits shift periodically, consulting accredited financial planners and reviewing current IRS guidelines ensures that retirement vehicles remain fully maximized each tax year.
💡 Navigating the twin demands of supporting aging relatives and launching young adults requires strategic clarity and open household discussions about financial boundaries.
🔍 Taking time to audit long-term savings accounts, healthcare directives, and retirement timelines today can prevent unexpected crises from derailing future plans.
👇 Are you currently balancing the needs of elderly parents alongside support for adult children? Share your perspectives and strategies with our community below.
 1
 2
 3
 4