
Harley-Davidson Stock Drops After Fiscal Q3 Earnings Miss Wall Street Estimates, Yet Management Unexpectedly Boosts Full-Year Forecast

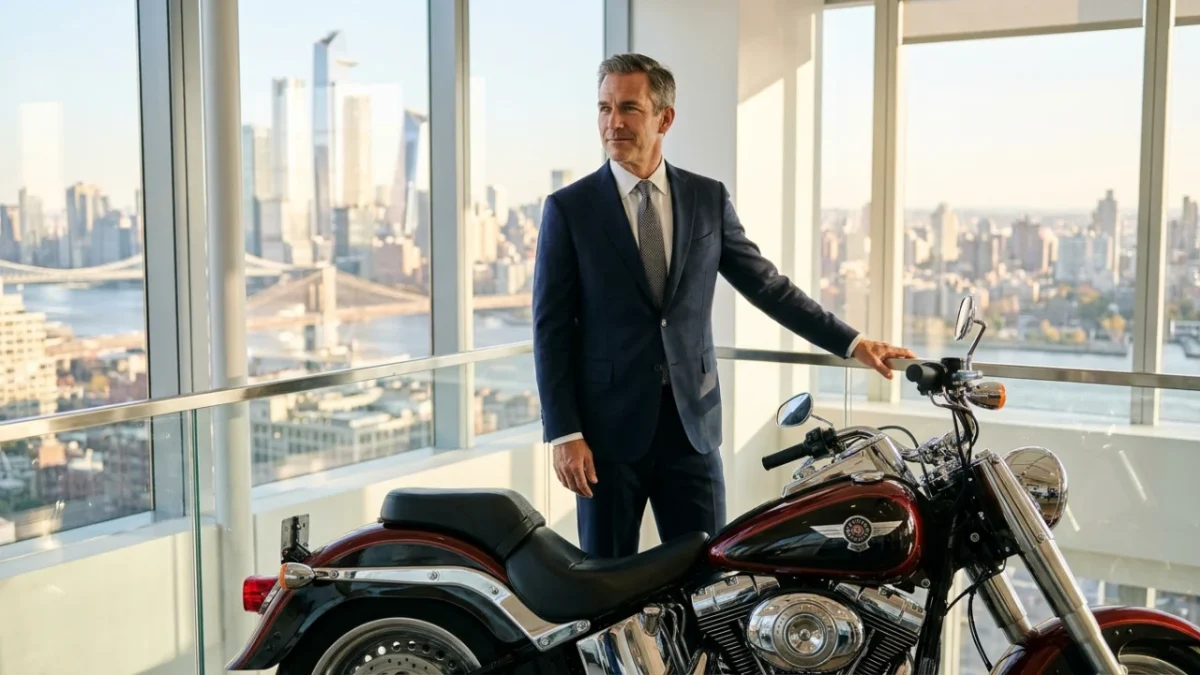
Harley Davidson stock stumbled after the iconic motorcycle maker delivered fiscal third-quarter earnings that fell short of Wall Street expectations. While traders initially punished the equity, company leadership countered the quarterly shortfall by raising its full-year guidance for global motorcycle retail sales and operating income across major business units.
The split between quarterly performance and executive confidence has triggered fresh debates across trading desks. Short-term headwinds clearly weighed on profitability during the quarter, yet corporate management is signaling that buyer demand and operational margins are primed for a stronger finish to the fiscal year.
That juxtaposition between immediate quarterly pain and forward-looking optimism reveals a complex narrative beneath the ticker symbol.
Inside the Q3 Earnings Miss and the Market Reaction
Wall Street entered the fiscal third-quarter reporting window expecting steadier operational execution from the Milwaukee-based brand. When reported numbers failed to meet consensus targets, market participants reacted swiftly, driving shares into negative territory during post-release trading.
Earnings misses often force institutional investors to recalibrate their immediate valuation models. For vehicle manufacturers, softer quarterly figures generally point to wholesale volume constraints, shifts in consumer financing costs, or dealer inventory rebalancing.
Quarterly volatility frequently obscures structural shifts in high-ticket consumer discretionary sectors, where retail momentum and financing margins carry more weight than a single three-month earnings report.
Yet the immediate selling pressure ran directly into an unexpected corporate upgrade.
The Counterintuitive Guidance Hike: What Management Sees Ahead
Rather than trimming forward projections to cushion the quarterly miss, executives did the exact opposite. The company officially raised its full-year outlook for global retail motorcycle sales, demonstrating confidence in end-market appetite.
In addition to volume improvements, leadership upgraded operating income projections across two foundational pillars of the enterprise:
- Motorcycle Segment: Upward revisions reflect anticipated improvements in global retail unit deliveries and healthier core manufacturing margins.
- Financial Services Segment: Raised operating expectations point toward solid loan portfolio performance and resilient retail credit operations.
The upgraded forecast suggests that internal indicators, dealer orders, and international showroom traffic remain far sturdier than the backward-looking third-quarter numbers implied.
Balancing Wholesale Deliveries and Retail Demand
A primary factor behind the divergence between earnings and guidance involves wholesale distribution timing. Factory shipments to dealership networks do not always sync cleanly with calendar quarters, creating temporary revenue lulls even when underlying consumer interest remains intact.
By lifting global retail sales targets, management indicated that showroom handoffs are stabilizing. The move signals that the quarterly shortfall was driven by operational timing rather than collapsing rider demand.
Myth vs. Reality: Reading the Corporate Signals
A common misconception across retail investing forums is that any earnings miss automatically signals cratering consumer demand for heavyweight touring bikes. In reality, modern automotive and motorcycle manufacturers run complex, multi-tiered operations where credit arms and global dealership pipelines dictate balance-sheet timing.
| Metric / Signal | Operational Reality |
|---|---|
| Fiscal Q3 Earnings | Fell below consensus Wall Street expectations, sparking an immediate share decline. |
| Full-Year Retail Sales | Management raised global unit targets, indicating resilient end-consumer showroom activity. |
| Motorcycle Segment Income | Full-year operating income expectations were revised upward despite the quarterly lag. |
| Financial Services Segment | Operating income outlook received a positive revision, showing credit-arm stability. |
Navigating these mixed signals requires market participants to look beyond the immediate headline print.
Key Steps for Evaluating the Brand’s Path Forward
For investors and industry observers assessing the durability of this revised outlook, several fundamental checkpoints will determine whether the company delivers on its raised bar:
- Track Dealer Inventory Levels: Monitor whether retail showroom sell-through keeps pace with the upgraded global volume projections.
- Evaluate Credit Health: Assess loan performance metrics and delinquency rates within the financial services division.
- Measure Operating Margin Execution: Watch the subsequent quarter to verify if the promised boost in operating income materializes on the bottom line.
The coming months will put corporate leadership’s bullish full-year targets to the test.
💬 Wall Street reacted to the short-term earnings miss, but management is betting big on a strong full-year finish.
✨ Tracking retail motorcycle sales against factory shipments will show whether the guidance hike was warranted.
📱 Drop your thoughts in the comments below and share how you view the company’s upgraded global outlook.
👇 Join the discussion and let us know what you expect from the stock moving forward.
 1
 2
 3
 4
