SpaceX Stuns Wall Street With a Massive $4.4 Billion Profit Even as Starship Cash Burn Crosses $9.9 Billion in a Single Quarter: Here Is the Full Reality
Space Exploration Technologies Corp. has shattered expectations by banking an unprecedented net income of $4.4 billion for the third quarter, reversing a steep $1.1 billion net loss from the same period last year even as it burned through more than $9.9 billion of free cash flow in just three months.
While global attention remains transfixed on every heavy SpaceX launch, rocket operations actually contributed the smallest slice to the company’s $14.6 billion quarterly turnover. The aerospace giant, which now commands a public market capitalisation of $1.98 trillion on the NASDAQ under the ticker SPCX, is undergoing an aggressive structural transformation that has caught both institutional funds and retail shareholders off guard.
The company’s top-line revenue surged 161% year over year, but the traditional space segment crawled ahead with a modest 6% increase to $1.8 billion. Instead, profitability was powered by high-margin connectivity and an extraordinary surge in artificial intelligence cloud services.
The AI Revenue Explosion Carrying Falcon 9 and Starship
The standout performer of the quarter was the Super Intelligence (SI) division, which skyrocketed by 830% compared to the prior-year period to hit $7.6 billion in revenue. Even without an August acquisition that contributed $608 million, the SI business expanded by 755% purely on organic expansion.
Demand for off-planet and terrestrial AI compute capacity has transformed the commercial profile of Space Exploration Technologies Corp. The SI division generated an operating income of $431 million, marking a complete turnaround from an operating loss of $1.7 billion recorded twelve months earlier.
The connectivity arm delivered comparable muscle, posting an operating profit of $2.4 billion on $5.2 billion in sales, up 69.5% year over year. The business is now pursuing access to 80,000 cell sites to expand its terrestrial footprint, moving well beyond basic consumer satellite dishes.
Starship Flight 14 and the Orbital Compute Architecture
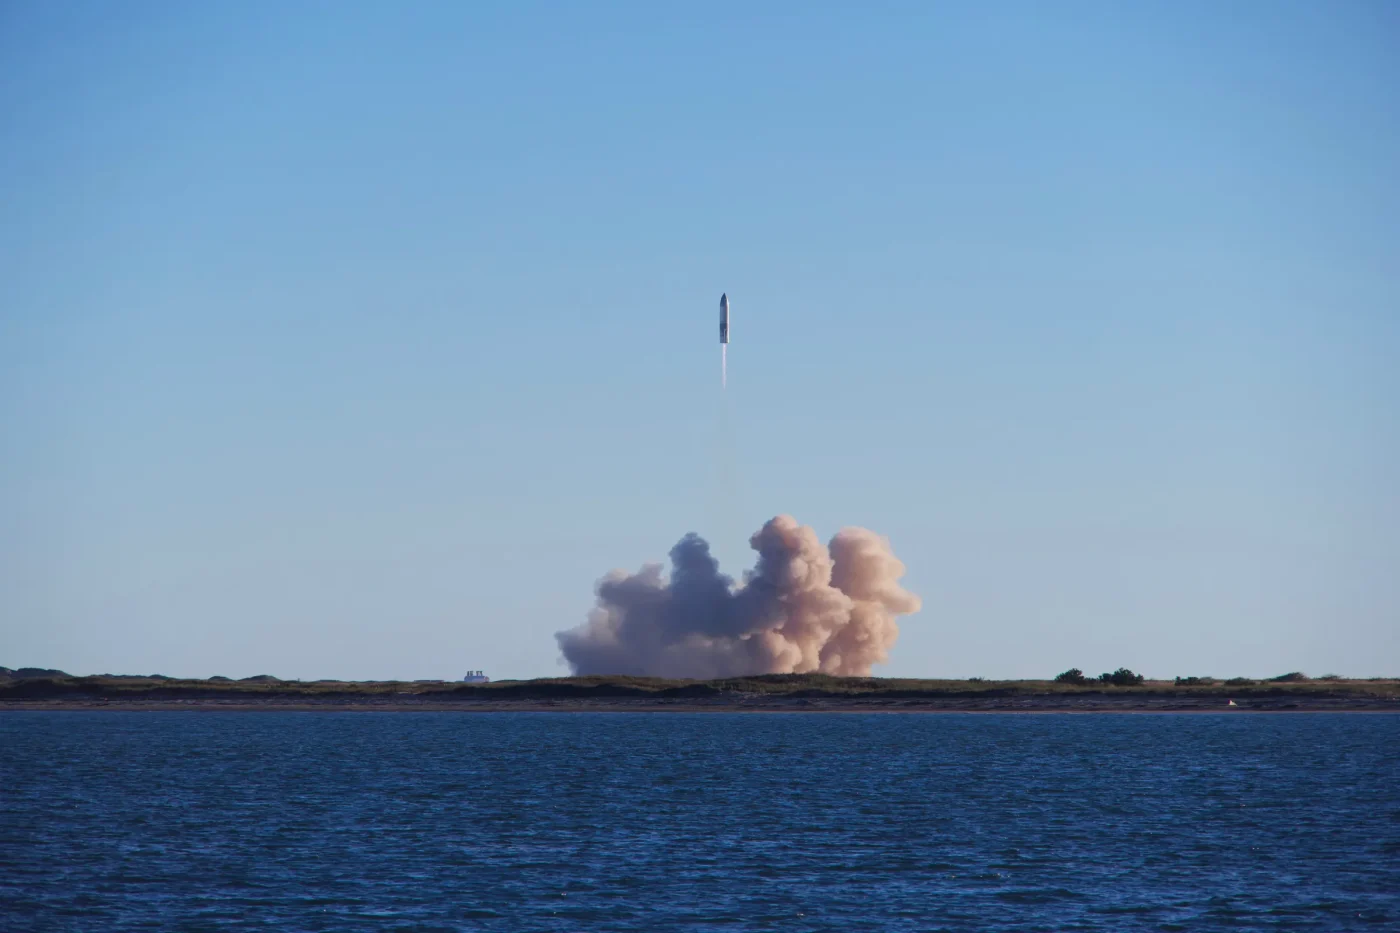
The hardware transition behind these balance-sheet figures centres on the operational debut of orbital heavy lift. SpaceX reached a milestone when Starship flight 14 completed an orbital flight carrying 26 Starlink V3 satellites, a deployment that standard Falcon 9 rockets lack the physical volume to transport.
SpaceX chief executive Elon Musk has outlined a multi-year road map to reach $1 trillion in annual revenue by 2030, with targets between $500 billion and $1 trillion contemplated as soon as next year. Achieving these figures relies heavily on shifting data processing directly into orbit through cost-effective launches.
- Drastic Launch Cost Compression: Starship’s fully reusable architecture aims to cut average orbital delivery costs by up to 99%, establishing viable margins for heavy orbital compute clusters.
- Next-Generation Constellation Capacity: Starlink V3 deployment unlocks greater data bandwidth and network capacity across international markets.
- Commercial AI Cloud Agreements: Enterprise demand for compute power has turned orbital communications into dedicated enterprise cloud pipelines.
- Cash Burn vs Capital Reserves: A quarterly cash burn exceeding $9.9 billion is offset by an $85.7 billion capital chest raised during the June public offering.
Valuation Pressures and the Reality of Capital Intensity
Despite the blowout quarter, the valuation arithmetic poses distinct risks for market participants. The stock trades at an eye-watering price-to-sales multiple of 68.5, baking in immense sustained growth across both connectivity and machine intelligence.
A burn rate nearing $10 billion per quarter means the company’s war chest cannot sustain indefinite friction. Regulatory approval delays, launch schedule interruptions, or an industry-wide slowdown in compute demand could quickly pinch working capital.
For investors tracking every operational milestone, each future SpaceX launch is no longer just an engineering showcase. It is the vital delivery mechanism required to keep the world’s most aggressive commercial infrastructure solvent.
💡 The convergence of heavy rocketry and orbital compute has altered how global technology conglomerates view space infrastructure. The race to balance high-burn capital expenditure against satellite margins is setting a fresh precedent for public markets.
🔍 As satellite architectures move into enterprise networking, legacy telecoms providers face mounting structural disruption. Whether SpaceX can hit its $1 trillion revenue target depends entirely on keeping Starship economics on course.
👇 Do you believe SpaceX can justify a valuation multiple near 70 times sales while burning billions on Starship development? Share your perspective in the comments below.
 1
 2
 3
 4