He Celebrated Zero Balance on His $62,000 Student Debt at Age 71 — Then Officials Clawed It Back After Ruling 15 Payments Void
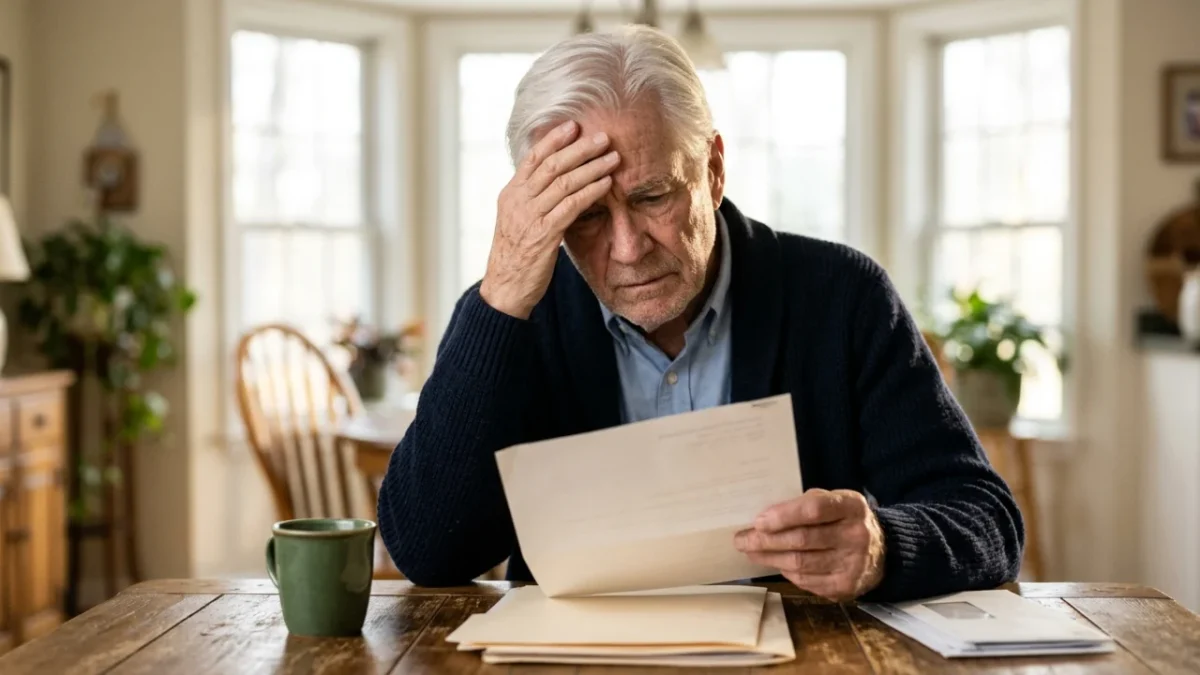
After dedicating more than a decade of public service to clear a £50,000 ($62,000) student debt, 71-year-old Donald Knierim received an official notice that his balance was wiped clean—only for federal authorities to abruptly claw the relief back months later.
The sudden reversal occurred after government auditors discovered that 15 historical payments had been erroneously classified as qualifying towards his balance discharge. Instead of enjoying a debt-free retirement, Knierim was cast back into active repayment, with his servicer demanding roughly 18 additional monthly instalments of approximately $470.
The shock has turned an earned retirement into a bureaucratic nightmare.
Knierim, who originally borrowed the funds to finance his children’s university education, spent over ten years working for Metra, Chicago’s commuter rail network. Under the regulations of the Public Service Loan Forgiveness (PSLF) scheme, ten years of full-time public employment paired with 120 qualifying monthly payments should have extinguished his remaining balance entirely.
In November 2025, his Federal Student Aid dashboard confirmed that every milestone had been satisfied. Believing the ordeal was finished, Knierim stepped down from his career to care for his unwell wife.
Then the automated promises collapsed.
How a Systemic Error Reopened a Cancelled Debt
Federal authorities later initiated an internal audit designed to rectify widespread coding inaccuracies across the national loan database. During that administrative clean-up, Knierim’s account was flagged and stripped of its discharge status.
The U.S. Department of Education confirmed it rescinded credits under the scheme after identifying that certain remittances failed statutory guidelines. In Knierim’s case, 15 payments made under the Temporary Expanded PSLF mechanism fell slightly below the mandatory baseline required by his income-driven repayment plan. Neither his servicer nor the software flagged the shortfall at the time.
Instead, the automated system logged each instalment as eligible, ticked off his final quota, and issued formal congratulations.
“I thought I was done, they gave me that notification that I was done, and then they clawed it back,” Knierim stated through Business Insider. “I have a flawless payment history. I have never missed a payment, and I paid what they told me to pay.”
Refusing to accept the sudden reinstatement of the liability, Knierim withheld the newly demanded sums while disputing the decision. The operational fallout was swift: his credit score plummeted by more than 200 points, leaving his file flagged as delinquent and facing imminent default.
Legal Relief Arrives While Individual Borrowers Remain Stranded
The dispute over administrative oversights unfolds alongside dramatic shifts in federal courtroom battles. Federal officials recently dropped their legal fight challenging regulations surrounding the Public Service Loan Forgiveness overhaul, effectively ending a high-stakes judicial standoff and safeguarding forgiveness protections for millions of public workers.
Yet while macro-level policy secures broader administrative relief, individual borrowers caught between historic software glitches and rigid criteria face immediate financial jeopardy.
Vital Defensive Measures for Every Public Service Borrower
Borrowers pursuing student loan forgiveness must take aggressive steps to safeguard their financial records against servicer discrepancies:
- Archive independent records: Do not rely exclusively on digital portals. Retain original bank statements, cleared debit receipts, and individual billing schedules.
- Download discharge paperwork immediately: Capture digital copies and physical prints of congratulatory letters, zero-balance dashboards, and servicer correspondence as soon as they appear.
- Audit payment allocations: Verify that each submitted payment aligns precisely with your certified income-driven plan rather than temporary bridging allowances.
- Monitor credit bureau reporting: Track your credit profiles regularly to challenge unjustified delinquency notices the moment a disputed balance surfaces.
For Knierim, returning to full-time work is impossible given family care obligations, leaving his financial future tied up in contested paperwork.
💡 Borrowers navigating public service programmes cannot afford to assume that official digital confirmations are infallible against future administrative audits.
🔍 Maintaining your own paper trail remains the only reliable safeguard against administrative clawbacks.
👇 Have you encountered errors or sudden reversals with your loan servicer? Share your experience in the comments below.
 1
 2
 3
 4